
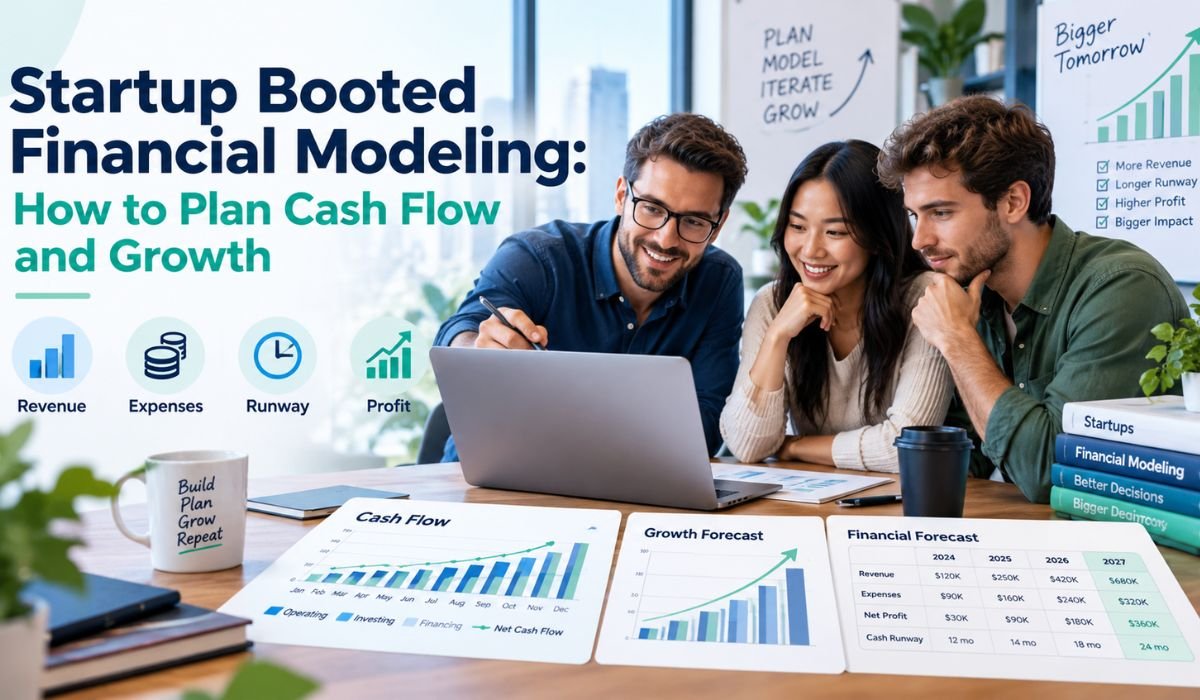
Building a Startup with your own money or early Customer Revenue can be liberating. Founders keep more control over decisions, priorities, and the direction of the company. The trade-off is that Financial Discipline becomes much more important. Without a large reserve of investor capital, a poorly timed hire, an expensive Marketing campaign, or an unexpected Inventory bill can put real pressure on Cash.
That is why Startup Booted Financial Modeling deserves attention. More commonly described as Financial Modeling for Bootstrapped Startups, it gives Founders a structured way to think about Revenue, Expenses, Cash Flow, and Growth before making major commitments.
A Financial Model isn’t a crystal ball, and it shouldn’t be treated like one. Its real value is helping a Founder explore reasonable possibilities. What happens if Customers take longer to pay? Can the Business afford another employee? How much Cash will be needed if Sales grow quickly? What happens if Revenue comes in below expectations?
For a Bootstrapped Startup, answering those questions can be more valuable than producing an impressive Revenue forecast. A strong model connects what happens inside the Business every day with Profitability, Cash availability, and Financial Risk.
Quick Financial Modeling Information
| Information | Details |
|---|---|
| Main Topic | Startup Booted Financial Modeling |
| Common Description | Financial Modeling For Bootstrapped Startups |
| Main Purpose | Financial Planning And Decision Support |
| Best Suited For | Bootstrapped And Self-Funded Startups |
| Core Focus | Cash Flow And Sustainable Growth |
| Starting Point | Business Assumptions |
| Common Revenue Drivers | Customers, Orders, Projects, Units, Or Subscriptions |
| Main Cost Groups | Fixed, Variable, Step, And One-Time Costs |
| Key Liquidity Measure | Available Cash |
| Sustainability Measure | Break-Even Point |
| Planning Measure | Cash Runway |
| Profitability Measure | Gross And Contribution Margin |
| Customer-Level Measure | Unit Economics |
| Useful Scenarios | Base, Downside, And Upside |
| Practical Forecast Interval | Monthly |
| Important Statements | Income, Balance Sheet, And Cash Flow Statements |
| Common Modeling Tool | Spreadsheet Software |
| Review Method | Forecast Versus Actual |
| Major Modeling Risk | Unrealistic Assumptions |
| Main Goal | Better Financial Decisions |
What Is Startup Booted Financial Modeling?
Startup Booted Financial Modeling is the process of turning Business assumptions into Financial Projections for a Startup that is self-funded or relies heavily on Customer Revenue. Those assumptions can cover everything from Pricing and Customer Growth to Payroll, Marketing Costs, Sales Volume, Supplier Expenses, and Payment Timing.
Imagine a Subscription Business preparing its Financial Forecast. The Founder might estimate how many paying Customers the company will have, how much each Customer will spend, how many Customers may leave, and what it will cost to provide the Service. Once those assumptions are connected, the model can estimate their effects on Revenue, Expenses, and Cash.
The crucial point is that assumptions are not facts. A Financial Projection represents what could happen based on the information available when the model is built.
That distinction matters. A useful Financial Model makes its assumptions visible instead of hiding them inside complicated formulas. As actual Business results become available, those assumptions can be tested, adjusted, and gradually replaced with better evidence.
Why Financial Modeling Matters
Bootstrapped companies often have less room for Financial mistakes than Businesses supported by substantial outside funding. When Cash is limited, even a promising opportunity needs to be considered alongside its cost and timing.
A Financial Model makes those trade-offs easier to see.
Hiring another employee might allow the company to serve more Customers, for instance, but it will also increase recurring Cash requirements. Reducing Prices could stimulate Sales while shrinking Contribution Margin. An E-Commerce company may experience rapid Revenue Growth but need to spend heavily on Inventory before receiving Cash from those Sales.
This is why Financial Modeling reaches far beyond accounting. It can influence Pricing, Hiring, Marketing, Purchasing, Expansion, Product Development, and other everyday Business Decisions.
It also encourages Founders to think in possibilities rather than certainties. Instead of building the company around one optimistic Growth forecast, management can prepare for stronger and weaker outcomes and decide how the Business would respond to each.
Build The Model Around Real Business Drivers
A useful Startup Financial Model begins with the Business itself, not with an elaborate Spreadsheet.
Every company has a handful of factors that drive its Financial Performance. Identifying those drivers is usually a better starting point than trying to create complicated formulas from day one.
For a SaaS company, important drivers could include Paying Customers, Subscription Prices, Churn, Customer Acquisition, and Service Costs. A Consulting Business might care more about Clients, Projects, Billable Capacity, Contractor Costs, and Customer Payment Terms. For an E-Commerce company, Orders, Average Order Value, Product Costs, Inventory, Returns, Shipping, and Payment Processing may matter most.
Keep those assumptions separate from the calculations whenever possible. Doing so makes the model easier to understand and much easier to update.
If expected Customer Growth changes, for example, the Founder should be able to adjust that assumption and see how the change flows through Revenue, Expenses, and Cash.
Over time, this process becomes increasingly useful. Forecast assumptions can be compared with actual Business results, helping the Founder discover which expectations were realistic and which need another look.
Forecast Revenue From The Bottom Up
Revenue Forecasting becomes more meaningful when it starts with activities the Business can actually measure.
For a straightforward Product Business, the basic relationship may be:
Revenue = Units Sold × Average Selling Price
The same principle can be adapted to other Business Models. A Service company could forecast the number of Clients or Projects and their Average Value. A Subscription Business may estimate Paying Customers and Average Revenue per Customer while accounting for new Customers and those who leave.
This is often called a Bottom-Up approach because the Forecast is built from operating drivers rather than starting with the size of the overall market.
Top-Down estimates still have a place. Understanding the potential market can help a Founder judge the scale of an opportunity. The problem comes when a Startup simply assumes it will capture a small percentage of a huge market without explaining how those Customers will actually be reached.
A useful operating Forecast connects Revenue expectations to Pricing, Customer Acquisition, Retention, Sales Capacity, and other real constraints.
Founders should also be cautious about projecting a brief period of exceptional Growth indefinitely. Early-stage results can move sharply from month to month, and a few strong periods don’t automatically establish a lasting trend.
Understand What Growth Really Costs
Revenue Growth looks attractive on a chart, but it rarely arrives without additional Costs.
Some expenses remain relatively stable within a particular operating range. These are commonly treated as Fixed Costs. Variable Costs move more directly with Sales or Production. Step Costs appear when the company reaches a level where additional capacity is necessary. One-Time Costs can include Equipment, Setup Expenses, Professional Services, or significant Development work.
Knowing how each Cost behaves makes a Financial Model far more informative.
Consider an online Retailer. More Sales may require the company to purchase additional Inventory before Customers place their Orders. A Service Business might need another employee before it has enough capacity to accept more work. A Software company could face higher Infrastructure and Customer Support Costs as usage expands.
Growth, in other words, can consume Cash before it produces additional available Cash.
A strong model therefore asks two questions together: How much Revenue could this Growth create, and how much money will the company need to support it?
Make Cash Flow The Center Of The Model
Perhaps the most important lesson for a Bootstrapped Founder is that Profit and Cash are not the same thing.
A company can record Revenue and report Accounting Profit while still struggling to meet immediate Financial Obligations. Suppose a Business Customer receives an invoice today but isn’t required to pay immediately. The Revenue and the Cash Collection may occur at different times, while Payroll, Suppliers, Software subscriptions, and other obligations continue to fall due.
At its simplest, Cash movement can be expressed as:
Ending Cash = Beginning Cash + Cash Inflows − Cash Outflows
The formula is easy. Estimating the timing correctly is the difficult part.
A realistic Cash Flow Forecast should consider when Customers are expected to pay, when Payroll is due, Supplier Payment Terms, Inventory Purchases, Taxes, Refunds, Debt Payments, Equipment Purchases, and recurring Operating Expenses.
Monthly Cash Forecasting can be particularly valuable for a Bootstrapped Startup. An annual projection might suggest that the company will finish the year in a healthy position while completely missing a serious Cash shortage halfway through it.
That is exactly the kind of problem a useful Financial Model should reveal before it happens.
Understand The Main Financial Statements
As a Startup develops, its Financial Model may become increasingly connected with formal Financial Statements.
The Income Statement records Revenue and Expenses over a period and shows whether the Business generated an Accounting Profit or Loss. The Balance Sheet provides a snapshot of Assets, Liabilities, and Owners’ or Shareholders’ Equity at a particular point in time. The Cash Flow Statement explains movements in Cash through Operating, Investing, and Financing activities. A Statement of Shareholders’ Equity may also show how Shareholders’ Equity changes over time.
These statements tell different parts of the same Financial story.
Suppose a company buys Inventory. Cash decreases, but the purchased Inventory may appear as an Asset on the Balance Sheet until the relevant accounting treatment changes as it is sold. Similarly, collecting an outstanding Customer Invoice increases Cash, but that collection doesn’t necessarily represent new Revenue at that moment if the Revenue was recognized earlier.
A Founder doesn’t need to become an accountant to create a useful operating model. Still, understanding these distinctions makes it much harder to mistake Accounting Profit for money that is actually available to spend.
Calculate Break-Even And Cash Runway Carefully
Break-Even Analysis gives Founders a practical way to estimate how much Business activity is required for modeled Contribution to cover relevant Costs.
For a simple single-product Business:
Contribution Per Unit = Selling Price − Variable Cost Per Unit
Suppose the Product sells for $120 and carries a Variable Cost of $40. That leaves an $80 Contribution Per Unit.
If relevant Fixed Costs total $12,000, the simplified calculation becomes:
Break-Even Units = $12,000 ÷ $80 = 150 Units
Under those assumptions, the Business would need to sell 150 units for Contribution to cover the modeled Fixed Costs.
Real companies are often more complicated. They may sell several Products with different Margins, experience changing Costs, pay financing expenses, or have expenses that don’t fit neatly into Fixed and Variable categories. Break-Even figures should therefore be treated as planning estimates rather than universal Financial thresholds.
Cash Runway answers another important question: how long might existing Cash support the Business?
A simple estimate is:
Cash Runway = Available Cash ÷ Average Monthly Net Cash Decline
That can be useful when Cash usage is fairly stable. When Revenue, Inventory purchases, Payroll, or other Cash movements vary substantially, however, a detailed month-by-month Cash Forecast provides a much clearer picture.
Measure Unit Economics Before Scaling
A company can grow Revenue quickly without building a healthy Business. That is why Unit Economics deserves attention before a Founder spends aggressively on expansion.
Unit Economics looks at Revenue and Costs at a meaningful level within the Business. The appropriate unit could be a Customer, Order, Subscription, Project, or Transaction.
Which metrics matter depends heavily on the Business Model.
A Service Business may care about Project Margin, Staff Capacity, and the cost of delivering each engagement. An E-Commerce company might concentrate on Product Margin, Shipping, Returns, Fulfillment, and repeat purchases. For SaaS companies, Recurring Revenue, Customer Retention, Customer Acquisition, and Service Costs can become particularly important.
Measures such as Contribution Margin, Customer Acquisition Cost, Retention, and Customer Lifetime Value can help when they genuinely fit the Business.
The broader principle is more important than any individual metric. Before investing heavily to create more Sales, a Founder should understand whether each additional unit of activity improves the Economics of the company or simply creates more Revenue alongside even more expense.
Use Scenario Planning Instead Of One Perfect Forecast
Every Financial Forecast contains uncertainty. Pretending otherwise doesn’t make the model more accurate.
Scenario Planning gives Founders a more useful way to handle that uncertainty.
A Base Case can represent the company’s reasonable current expectations. A Downside Case can show what happens if Sales disappoint, Costs rise, Customers pay later, or another important assumption weakens. An Upside Case can explore stronger performance and the resources required to support it.
The scenarios should change more than the Revenue line.
If Sales rise rapidly, the company may need additional Inventory, Customer Support, Infrastructure, Fulfillment Capacity, or Employees. If Sales fall, many Costs won’t disappear immediately. Rent, Payroll, Software subscriptions, and other commitments may continue.
Good Scenario Planning eventually leads to action. A Founder might decide that Hiring will be delayed if Cash falls below a certain level, or that Marketing Spending can increase once Customer Economics reach an acceptable range.
That turns the Financial Model from a passive forecast into a genuine management tool.
Do Not Ignore Working Capital
Working Capital is one of the easiest areas for a growing Business to underestimate.
Imagine a company that pays its Supplier before receiving Inventory. It then stores that Inventory, eventually sells the Product, and perhaps waits again before collecting Customer Payment. The Sale may ultimately be profitable, but Cash has been committed throughout much of that cycle.
The same problem can appear in Service Businesses when Customers take weeks to pay invoices.
Accounts Receivable, Accounts Payable, Inventory, and Payment Timing should therefore be incorporated into the Financial Model whenever they materially affect the Business.
This becomes even more important during rapid expansion. Higher Sales can create a greater need for Inventory or short-term operating Cash. As a result, a growing company can experience tighter liquidity even while its Revenue is moving in the right direction.
That is why Founders shouldn’t judge Financial Health from Revenue Growth alone.
Match The Model To The Startup
There is no universal Startup Financial Model.
A SaaS company may emphasize Subscriptions, Recurring Revenue, Customer Growth, Churn, Acquisition, and Service Costs. A Service Business is more likely to focus on Projects, Staff Utilization, Client Payments, Payroll, and Contractor Expenses. E-Commerce Businesses often need detailed assumptions for Orders, Average Order Value, Product Costs, Inventory, Shipping, Returns, and Fulfillment. Marketplace companies may concentrate on Transaction Volume, Active Participants, Platform Fees, and Operating Costs.
The mistake is assuming that every Startup needs every popular Financial metric.
It doesn’t.
A Founder should focus on the numbers that explain how that particular company earns Revenue, spends Cash, delivers its Product or Service, and grows.
A smaller Financial Model that management understands and actually uses is usually more valuable than an enormous Spreadsheet filled with metrics nobody can explain.
Bootstrapped And Venture-Backed Planning Are Different
A Bootstrapped Startup and a heavily Venture-Backed company may look at Growth through very different Financial lenses.
For a Bootstrapped company, Customer Revenue, Cash Preservation, controlled Hiring, and sustainable Unit Economics may carry particular weight. The Founder cannot simply assume that another funding round will arrive whenever the Cash Balance gets uncomfortable.
Some Venture-Backed Businesses, by contrast, may deliberately accept significant short-term losses when outside capital is financing a strategy built around rapid Growth.
That doesn’t make either approach inherently better.
The right strategy depends on the Business Model, available Capital, market opportunity, competitive conditions, Founder objectives, and appetite for Risk.
For Bootstrapped Founders, though, one relationship deserves constant attention. Faster Growth may look exciting, but if supporting that Growth consumes Cash faster than the company can reasonably finance it, expansion can create Financial Stress rather than Financial Strength.
The Financial Model should make that trade-off visible.
Review Forecasts Against Actual Results
A Financial Model shouldn’t be created once and forgotten in a folder. Its usefulness increases when it is compared with what actually happens.
At regular intervals, compare Forecast Revenue with Actual Revenue, Forecast Expenses with Actual Expenses, and projected Cash with the real Cash Balance. When there is a meaningful difference, investigate it.
Perhaps Sales were weaker than expected. Maybe Customer Payments arrived later than assumed. Advertising became more expensive, Supplier Prices increased, or Gross Margin changed.
Those differences aren’t simply forecasting failures. They’re information.
Each variance gives the Founder another opportunity to understand the Business and improve the next Forecast. Over time, assumptions that were initially based on limited information can be replaced with patterns drawn from the company’s own operating history.
A monthly Forecast-versus-Actual review is practical for many early-stage companies. Businesses dealing with rapid changes or tight liquidity may need to monitor Cash more frequently.
The objective isn’t to make every forecast perfectly accurate. It is to keep learning from the gap between expectation and reality.
Use AI And Financial Tools With Human Oversight
AI has made parts of Financial Modeling easier and faster. Founders can use modern tools to organize assumptions, explain Spreadsheet formulas, explore scenarios, summarize variances, and flag possible inconsistencies.
Those capabilities can save time, particularly for people who aren’t Financial specialists.
They don’t eliminate the need for judgment.
An AI system can work from a flawed assumption, misunderstand context, produce an incorrect formula, or suggest an Accounting treatment that doesn’t fit the company’s circumstances. A polished output isn’t automatically an accurate one.
Important calculations should therefore be checked against the underlying Business Records and reviewed by someone who understands how the company operates.
There is also a point at which professional help becomes sensible. Complex Tax matters, Debt, Equity arrangements, Fundraising, multiple Business entities, formal Financial Reporting, and complicated Accounting questions can require expertise beyond a Founder-built Spreadsheet.
Technology can support Financial Judgment. It shouldn’t replace it.
Final Thoughts
Startup Booted Financial Modeling isn’t valuable because it can produce a sophisticated Spreadsheet. Its real value lies in helping a Founder understand how the Business behaves financially.
A strong model connects Revenue with Costs, Cash Flow, Working Capital, Unit Economics, and Growth. It makes important assumptions visible, allows different outcomes to be tested, and becomes more useful as Forecasts are compared with Actual Results.
For a Bootstrapped Startup, Cash deserves particular attention. Profitability matters, but Accounting Profit doesn’t guarantee that enough Cash will be available when Payroll, Suppliers, Inventory, Taxes, or other obligations become due. Even rapid Growth can create pressure if the company needs to spend money before receiving the Cash generated by additional Sales.
That is why the best Financial Models aren’t static predictions. They evolve alongside the Business.
As Founders gather more real-world information, they can replace uncertain assumptions with actual operating experience, refine their scenarios, and make decisions with a clearer understanding of the Financial consequences.
Technology, including AI, can make that process faster in 2026, but it doesn’t change the basic principle. Sustainable Growth still depends on understanding how the company earns money, where its Cash goes, what expansion costs, and how much Financial flexibility remains.
For a Founder building without a large external funding cushion, that understanding isn’t simply useful. It can shape the difference between Growth that looks impressive on paper and Growth the Business can actually sustain.
FAQs About Startup Booted Financial Modeling
What Is Startup Booted Financial Modeling?
Startup Booted Financial Modeling is a structured method of estimating Revenue, Costs, Cash Flow, and future Financial Performance for a Bootstrapped Startup. It connects operating assumptions with possible Financial outcomes, allowing Founders to explore how different Business decisions or conditions may affect Cash and Growth.
What Should A Startup Financial Model Include?
A useful model should clearly show its assumptions, Revenue Drivers, Operating Costs, Cash Inflows, Cash Outflows, and Financial Projections. Depending on the company, it may also cover Working Capital, Unit Economics, Break-Even Analysis, Financial Statements, and different Growth scenarios. The model should reflect how the specific Business actually operates rather than copying unnecessary metrics from another company.
Can A Pre-Revenue Startup Build A Financial Model?
Yes. A Pre-Revenue Startup can estimate Pricing, Customer Growth, Product Development Costs, Marketing, Hiring, and expected Cash requirements. With little or no operating history, however, those projections depend heavily on assumptions. Founders should make the assumptions clear and update them as Customer feedback, Sales activity, and real Financial Data become available.
How Do You Forecast Startup Cash Flow?
Begin with available Cash and estimate when money is expected to enter and leave the Business. Customer collections should be modeled according to expected Payment Timing rather than assuming every Sale immediately becomes Cash. Expected Payroll, Supplier Bills, Inventory, Taxes, Debt Payments, and other Cash requirements should then be included. Monthly projections can reveal short-term shortages that annual figures may conceal.
How Is Startup Runway Calculated?
A simplified Runway estimate divides available Cash by the average Monthly Net Cash Decline. This works best as a rough planning measure when Cash usage is relatively stable. If Revenue, Expenses, Inventory Purchases, or other Cash movements vary significantly, a detailed month-by-month Cash Forecast will usually provide a more meaningful view.
How Often Should A Financial Model Be Updated?
There is no single schedule that fits every Startup. A monthly review is practical for many Early-Stage Businesses because it allows Founders to compare Forecasts with Actual Results and revise assumptions. Companies experiencing rapid Growth, major operational changes, or limited Cash may need to monitor their Cash position more frequently.
Can AI Build A Startup Financial Model?
AI can help create model structures, explain formulas, organize information, develop scenario ideas, and review possible inconsistencies. Its output still needs verification. Important Financial, Accounting, Tax, or investment decisions shouldn’t rely solely on AI-generated assumptions or calculations without appropriate human review.
What Is The Biggest Startup Financial Modeling Mistake?
One of the biggest mistakes is treating assumptions as if they were guaranteed results. A model can appear extremely healthy when Revenue is overestimated or Costs, Payment Delays, Working Capital, and Growth requirements are underestimated. A useful Financial Model should make uncertainty visible rather than hiding it behind precise-looking numbers.
Learn more and explore exciting content on: What Is a Content Roadmap? A Complete Guide to Smarter Planning


Leave a Reply